Roofers fleet insurance for ladder vans, roof racks and small tippers
Insure the roofing firm's vans, ladder racks and waste tipper together, with one schedule to keep up to date. Answer a few questions once and specialist brokers who know roofing contractors will be in touch.
- Ladders and racks on the roof
- Slates, felt and lead carried
- Small tippers for strip-out
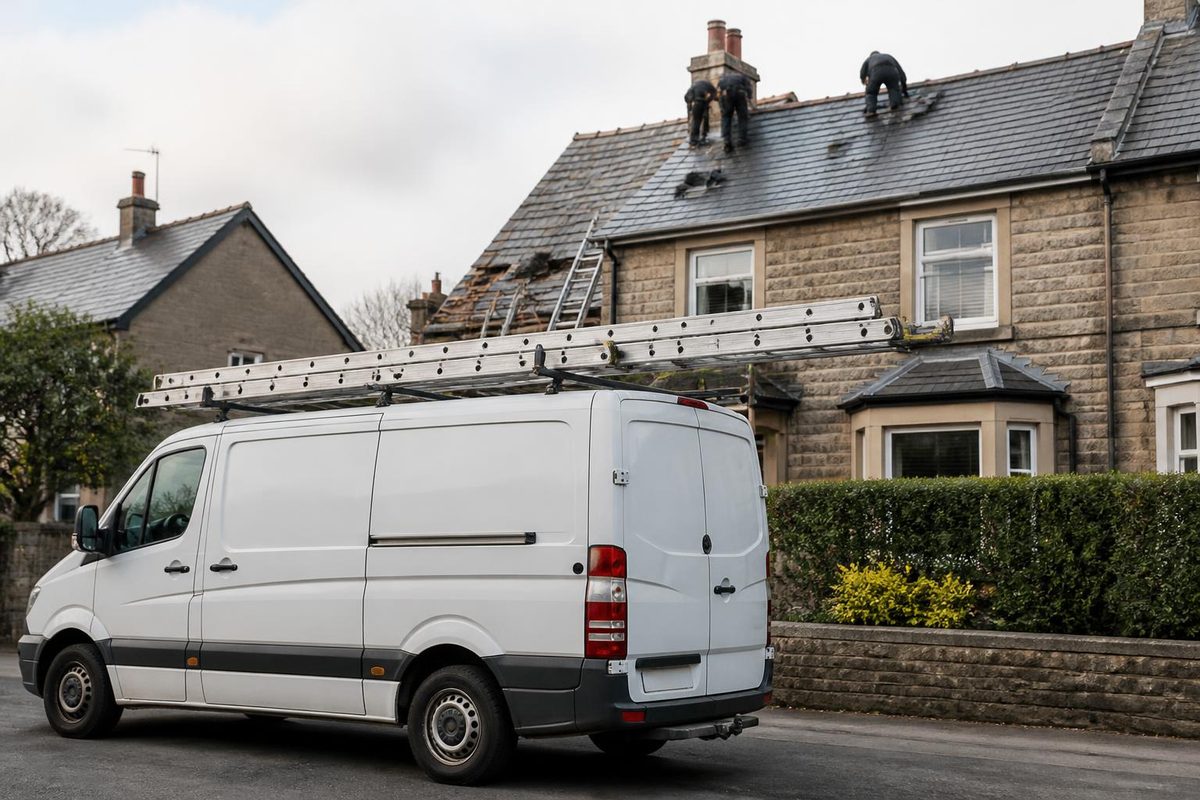
Roofers fleet insurance in brief
Roofers fleet insurance is one motor policy for the vans and small tippers a roofing contractor runs, covering them together instead of one by one. It belongs within fleet insurance for trades, with its own concerns about roof-rack loads, heavy materials and theft.
Roofing vans carry ladders and access kit on top and slates, tiles, felt and sometimes lead inside, so they are often heavier than they look. A broker will ask how ladders are locked, where vans park at night and what the tipper carries away from each job.
On the roof rack
Ladders, racks and roof-rack loads: what insurers look at
Every roofing van carries something on top. The rack, the ladders and anything tied to them change the vehicle's height, its handling and how attractive it is to thieves.
Ladders and roof ladders
Extension ladders and roof ladders are expensive and quick to steal from an unattended van.
- Lockable ladder clamps are often asked about
- Ladders are usually insured with tools, not the van
- Theft without forced entry may not be covered
Ladder racks and fitted equipment
The rack itself adds to the van's value and needs to be part of the vehicle description.
- Declare racks and roller systems when listing vans
- Extra height matters for car parks and bridges
- Signwriting and racking can affect repair costs
Long items tied on top
Battens, guttering and lengths of timber sometimes travel on the rack.
- Poorly tied loads can fall into traffic
- Damage caused by a lost load is a third-party claim
- Roof rack weight limits are worth knowing
Inside the van
Slates, felt, lead and the waste tipper
A roofing firm's vans are working vehicles carrying the firm's own materials and waste. That is usually own goods use, but the load still shapes the risk.
- Slates, tiles and felt: Heavy and bulky, so a fully loaded van can sit close to its gross weight. Insurers may ask about overloading.
- Lead and flashing: Valuable and easy to sell on, which makes vans carrying lead a theft target, especially overnight.
- Strip-out waste: Old tiles, rotten battens and torn felt stripped from the firm's own roofs still count as own goods.
- Small tippers: Many roofers run a tipper of up to 3.5 tonnes for waste and materials, often driven on a car licence.
The general points on load space, racking and class of use are covered on van fleet insurance. Tippers heavier than 3.5 tonnes are usually insured as lorries.
Working at height
Where the motor policy stops and roofing liability begins
Most of the serious risks in roofing happen on the roof, not on the road. A fleet policy covers vehicles; a fall, a dropped slate or a fire from a torch-on felt job is a liability question.
Covered by the fleet policy
The vans and tippers themselves, whether moving or parked, plus harm they do to other people and property.
- A van reversing into a client's gate
- A load falling from the roof rack
- Theft of or damage to the vans
Covered elsewhere
Injury or damage caused by the roofing work itself.
- Slates or tools falling onto the public
- Water getting in after a roof is stripped
- Injury to the firm's own roofers
Those risks sit with public liability insurance for roofing work and with employers' liability for staff, both separate from the fleet.
Before you call
What a roofing firm needs ready for the quote
Brokers who insure roofing businesses tend to start with theft and parking, then move on to drivers and the tipper.
- Overnight parkingLocked yard, driveway or street, and whether ladders stay on.
- Ladder and van securityLadder locks, deadlocks, alarms and trackers.
- What is carriedSlates, felt, lead and other materials left in vans.
- Tipper useYour own waste only, or waste for others too.
- DriversExperienced roofers, labourers and whether under-25s drive the tipper.
- Area workedMainly local domestic work or travel to commercial sites.
- Claims historyLadder and lead thefts, break-ins and road accidents.
How it works
One quote form, specialist fleet brokers
Insure Fleet is an information site, not an insurer or a broker. We link you to MyMoneyComparison.com, a comparison service that gives businesses a gateway to brokers who arrange fleet insurance every day.
Start your quote
Get my fleet quote takes you to our partner, MyMoneyComparison.com.
Describe the roofing vans
The form asks about the vehicles, the work they do and who drives, so you can be matched with a specialist fleet broker.
Compare and decide
A broker contacts you with options, subject to insurers' acceptance criteria. There is no obligation to buy.
Before you buy
Questions to put to the broker about a roofing fleet
Roofing fleets are often caught out by theft conditions and roof-rack exclusions. These questions bring them out early.
- Are ladders covered if stolen from the rack?Many policies only cover them under separate tools cover.
- Is lead in the van covered overnight?Limits and conditions often apply to materials left in vans.
- Does the rack need declaring?Racks and roller systems usually count as changes to the van.
- Is the tipper on the same terms?Some insurers rate tippers differently from panel vans.
- What if a load falls from the roof rack?Check it is handled as a normal third-party claim.
- Is a replacement van included?A roofer without a van loses days of work, especially in dry weather.
FAQs
Roofers fleet insurance questions
What is roofers fleet insurance?
Roofers fleet insurance is one motor policy covering the vans, pickups and small tippers run by a roofing contractor. One renewal date replaces several, and the schedule names the permitted use and drivers for every van.
Are ladders on the roof rack covered by the fleet policy?
Usually not as ladders. The fleet policy covers the van and any fitted rack declared as part of it. Ladders and access kit are normally insured as tools, under a separate policy or an add-on that may set conditions for overnight theft.
Is lead carried in the van insured?
The motor policy does not usually cover materials in the van. Lead and other stock are normally covered by a tools and materials policy, which may limit cover overnight or ask for vans to be locked and alarmed.
Do roofers need public liability as well as fleet cover?
Many roofing firms carry both, because the fleet policy only deals with vehicles. Falling slates, tools dropped from a roof or water damage after stripping are liability matters, and main contractors often ask for evidence of that cover.
Can a family roofing business put home and work vehicles together?
Some can. A small family firm with a couple of works vans and household cars may suit a mini fleet policy, while a firm adding vans as it takes on staff can look at small fleet insurance.
Is the scaffolding on a job covered by the roofer's fleet?
No. Roofers usually hire scaffolding from a scaffolding contractor, whose lorries are covered under scaffolding fleet insurance. The roofer's fleet policy covers only the roofer's own vehicles.
Does Insure Fleet sell insurance?
No. Insure Fleet is an information site and an affiliate of MyMoneyComparison.com, a comparison service that gives businesses a gateway to specialist brokers. When you start a quote you continue to MyMoneyComparison.com, and we may be paid a small commission if you are matched with and speak to a broker.
Ready to cover your roofing vans?
Describe the vans, racks and tipper on one form and hear from a specialist broker.