Demolition contractor fleet insurance for grab lorries, skip lorries and crew vans
Grab lorries, skip-type lorries and the vans that take crews to strip-out and demolition jobs, insured on one schedule. Complete one form to reach specialist brokers who take on demolition work.
- Grab and skip-type lorries
- Your own demolition waste
- Crew vans to every job
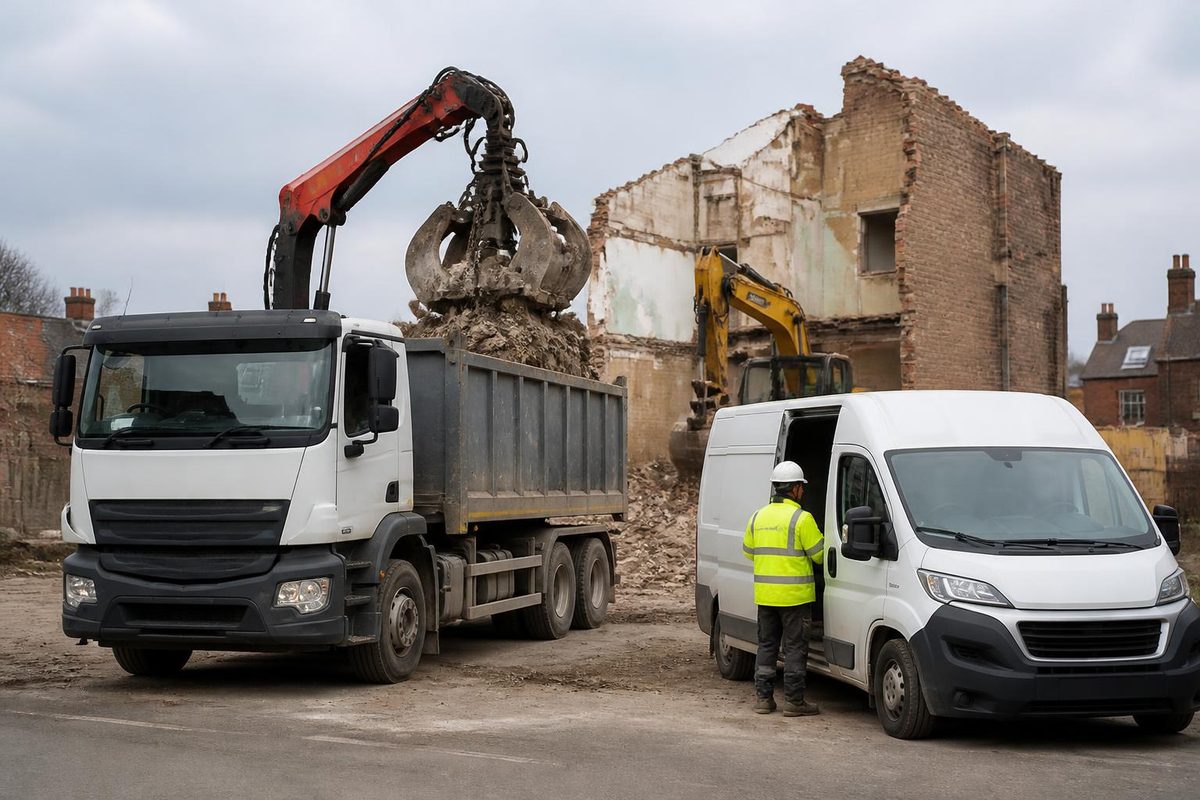
Demolition contractor fleet insurance in brief
Demolition contractor fleet insurance is one motor policy covering the grab lorries, skip-type lorries, crew vans and support vehicles a demolition firm uses. It sits at the specialist end of fleet insurance for trades, and fewer insurers are willing to look at it than for most building work.
The lorries carry heavy, awkward loads of rubble, steel and timber away from site, and the crews work on structures being taken down, sometimes where hazardous materials are present. Insurers want a clear picture of the lorries, the waste they carry and the type of jobs the firm takes on.
The vehicles
Which vehicles does a demolition firm usually run?
A demolition fleet is weighted towards heavy lorries. Most of them are goods vehicles over 3.5 tonnes, and the lorry side is covered more fully on HGV fleet insurance.
Waste and loads
Carrying demolition waste: own goods or hire and reward?
Demolition firms carry a lot of waste, and how it is described on the policy matters. Most of it belongs to the firm's own jobs, but skip work for others changes the class of use.
- Own demolition waste: Rubble, timber and steel cleared off the firm's own contracts counts as carriage of own goods in most cases.
- Waste for other firms: Lifting skips or clearing waste for other businesses in return for a fee counts as hire and reward, so the insurer has to be told.
- Scrap metal: Steel and other metals recovered from site and taken to a merchant, usually still your own goods.
- Plant movements: Moving your own excavators and breakers between sites on a low loader.
For a single grab lorry or skip lorry, or to look at lorry body types in more detail, HGV insurance for individual lorries is run by the same team.
A specialist trade
Why insurers treat demolition firms as specialist risks
Some insurers do not cover demolition at all, and those that do usually want detail about the jobs as well as the vehicles. Three areas come up most.
Sites with hazardous materials
Some jobs involve materials such as asbestos, removed by licensed specialists before or during demolition.
- Insurers may ask whether the firm takes on this work
- Vehicles used on those sites may be asked about
- Cleaning and handling of loads is worth describing
Lorry-mounted grabs
A grab lorry is a vehicle on the road and a lifting machine on site.
- Declare the grab as part of the lorry value
- Damage while the grab is working may need other cover
- Operator experience is often checked
Busy urban sites
Lorries enter and leave sites on tight streets with pedestrians close by.
- Banksmen at site gates are commonly asked about
- Cameras and sensors on lorries can help
- Turning in narrow streets raises the risk of strikes
Preparing the quote
What a demolition contractor needs to tell the broker
With fewer insurers willing to quote, a complete and accurate picture of the firm helps a broker approach the right ones.
- Lorry types and weightsGrab, skip, hook loader and low loader, with weights and values.
- Operator licenceLicence held for the lorries and the operating centre used.
- Type of jobsSoft strip, full demolition, industrial or residential work.
- Hazardous material workWhether any jobs involve materials such as asbestos.
- Waste carried for othersAny skip or waste work done for payment.
- Driver experienceLorry entitlement, experience and any convictions.
- Claims recordRoad accidents, lorry damage and third-party claims in recent years.
- Vehicle safety kitCameras, side sensors and warning systems fitted.
How it works
One quote form, specialist fleet brokers
Insure Fleet is an information site, not an insurer or a broker. We link you to MyMoneyComparison.com, a comparison service that gives businesses a gateway to brokers who arrange fleet insurance every day.
Start your quote
Get my fleet quote takes you to our partner, MyMoneyComparison.com.
Describe the demolition fleet
The form asks about the vehicles, the work they do and who drives, so you can be matched with a specialist fleet broker.
Compare and decide
A broker contacts you with options, subject to insurers' acceptance criteria. There is no obligation to buy.
Before you buy
Questions worth asking about a demolition fleet policy
Demolition firms carry unusual risks, so it pays to check the edges of the cover before a claim.
- Is the grab covered while working?Many motor policies cover the lorry on the road only.
- Does skip work for others need declaring?Paid waste work is usually hire and reward.
- Are hazardous material jobs excluded?Some insurers exclude vehicles used on certain sites.
- Who can drive the grab lorries?Age and experience limits are common for heavier lorries.
- Is a replacement lorry available?A grab lorry off the road can halt waste removal on site.
- Are low loaders and plant on them covered?The plant carried usually needs its own cover.
FAQs
Demolition contractor fleet insurance questions
What is demolition contractor fleet insurance?
Demolition contractor fleet insurance is one motor policy for the grab lorries, skip-type lorries, crew vans and other vehicles a demolition firm runs. Lorries and vans sit on one schedule, with the permitted drivers and class of use set out for each.
Why is demolition harder to insure than other building work?
Some insurers see demolition as higher risk because of heavy lorries, busy sites and the nature of the work, and some do not cover it at all. Those that do often ask detailed questions about the jobs, the waste carried and the drivers.
Is carrying demolition waste own goods use?
Usually, when the waste comes from your own jobs. Collecting skips or waste for other businesses for payment is hire and reward, so it is worth telling the broker if the firm does any of that work.
Does the policy cover the grab arm on the lorry?
When the lorry is on the road, the grab counts as part of it, so include it when stating what the lorry is worth. Once the arm starts loading on site, any damage it does may fall outside motor cover, and some contractors add a separate extension for that.
Can a small demolition firm get fleet cover?
Yes, though options may be narrower. A firm with a couple of lorries and a crew van can look at small fleet insurance, and firms that also dig out and level the site afterwards may find groundworks fleet insurance relevant too.
What if a neighbouring building is damaged during demolition?
Only where a vehicle did the damage, for example a grab lorry clipping a party wall while manoeuvring. Cracks or collapse caused by the demolition itself are a question for public liability insurance, not the motor fleet.
Does Insure Fleet sell insurance?
No. Insure Fleet is an information site and an affiliate of MyMoneyComparison.com, a comparison service that gives businesses a gateway to specialist brokers. When you start a quote you continue to MyMoneyComparison.com, and we may be paid a small commission if you are matched with and speak to a broker.
Ready to quote for your demolition fleet?
Set out the lorries and vans once and hear from brokers who take on demolition work.