Charity fleet insurance for vans, minibuses and volunteer drivers
The collection vans, shop vans and minibuses a charity or community group runs, insured together with drivers who may be staff or volunteers. One short form puts you in touch with specialist brokers who arrange cover for charities across the UK.
- Volunteer and staff drivers
- Donated goods collections
- Shop vans and minibuses together
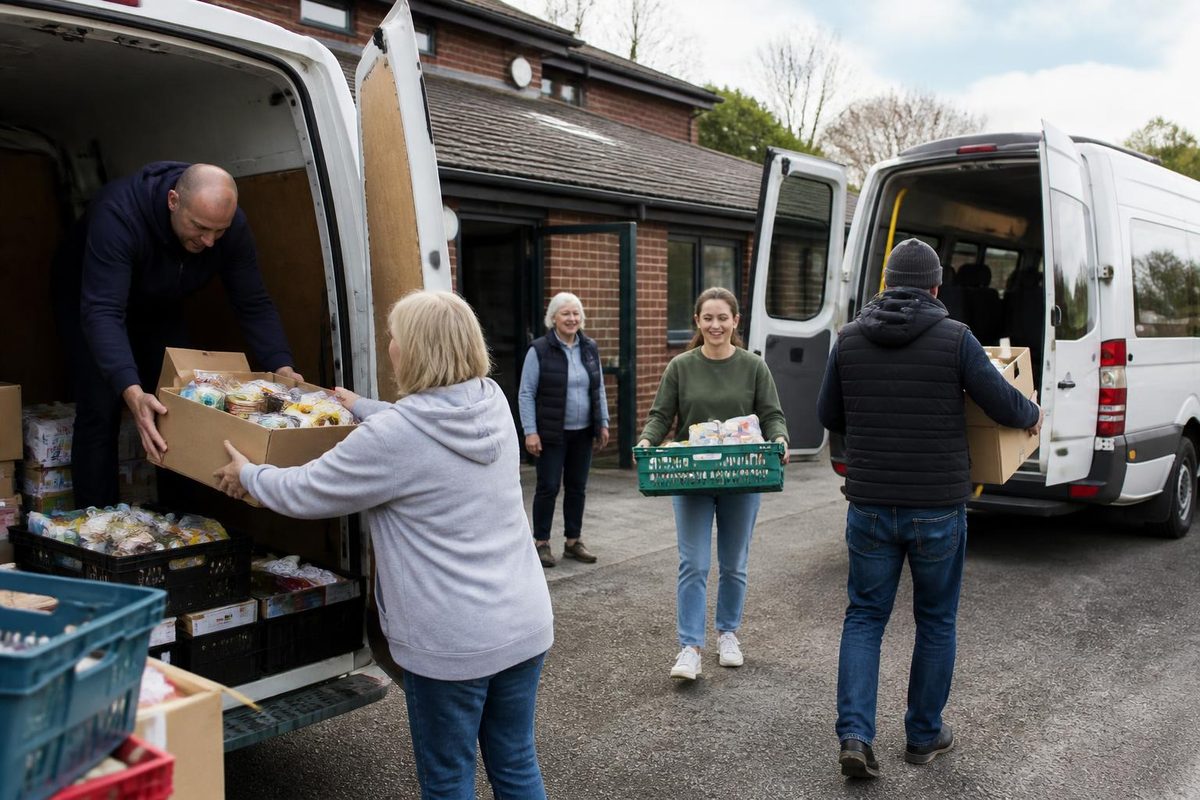
Charity fleet insurance in brief
Charity fleet insurance is one motor policy that covers the vans, minibuses and cars owned or leased by a charity or community group, so each vehicle does not need a policy of its own. It is a close cousin of fleet insurance for trades, but the driver list looks very different: retired volunteers, part-time staff and trustees may all take a turn behind the wheel.
Insurers want to know what each vehicle does, from collecting donated sofas to taking older people to lunch clubs, and how the charity decides who is allowed to drive.
The vehicles
What vehicles do charities and community groups run?
A charity fleet often grows one donated or grant-funded vehicle at a time. Vans for collections are usually the largest group, which is why the terms often start from van fleet insurance and add minibuses and cars alongside.
Volunteer drivers
Can volunteers drive the charity's vehicles?
Usually, yes, if they meet the insurer's driver terms. Volunteer drivers are where charity fleet cover differs most from a business fleet, because the pool of drivers changes often and covers a wide range of ages.
Older and younger volunteers
Many charity drivers are retired. Some insurers set an upper age, or ask for extra checks above a certain age, as well as a minimum age.
- Age limits differ between insurers
- Some ask for a health declaration
- Younger volunteers may face a higher excess
Licence checks and entitlement
The charity is usually expected to check each volunteer's licence before they drive and from time to time afterwards.
- Points and recent bans need declaring
- Larger vans and minibuses need the right entitlement
- Keeping a record of checks helps at claim time
Named volunteers or any driver
A small group of regular volunteers can be named. A charity with a changing rota may prefer any driver fleet insurance with set conditions.
- Named drivers suit a steady team
- Open driving suits a changing rota
- Conditions usually still apply to every driver
Everyday use
Donated goods, charity shops and community transport
Most charity vehicles carry the charity's own goods or its own clients, which keeps the class of use fairly simple. The questions start when passengers pay, vehicles are lent out or staff use their own cars.
- Donated goods: Collecting items people have given to the charity is normally treated as carrying the charity's own goods.
- Shop runs: Moving stock between shops and a warehouse, often by a volunteer driving the same route each week.
- Passengers: Carrying clients or members without charge is one thing; charging fares or asking for donations for travel is another. Charities running regular passenger services can compare notes on minibus fleet insurance, which covers permits and passenger seats.
- Lending vehicles: Lending a van or minibus to a partner group can fall outside the policy unless it is agreed with the insurer.
- Staff and volunteers' own cars: Volunteers using their own cars for the charity are not on the fleet policy. That sits with each driver's own insurer, as explained on grey fleet insurance.
Before the quote
What do insurers ask a charity about its vehicles?
Brokers who work with charities ask much the same questions each time. Gathering the answers before starting keeps things simple for trustees and staff.
- Each vehicle's jobCollections, shop runs, passenger trips, food deliveries or outreach visits.
- Who drivesEmployed staff, regular volunteers and occasional helpers, with ages and licence details.
- Driver checksHow licences are checked and how often, and any driver training or assessments.
- Where vehicles are keptA charity's yard, a shop car park or a volunteer's home overnight.
- PassengersWho travels, whether they pay anything, and any wheelchair access on board.
- Donated or older vehiclesAge, value and condition, including vehicles given to the charity.
- Previous claimsAccidents, thefts and damage across the fleet in recent years.
Alongside the motor policy
Covers that sit next to a charity fleet policy
The fleet policy covers the vehicles and harm they do on the road. Other parts of a charity's work need their own cover.
Lifting and carrying in homes
Volunteers carrying a wardrobe down a donor's stairs can damage a wall or hurt someone, which is not a motor claim.
- Usually a public liability question
- Worth mentioning when arranging cover
- Public liability cover
Stock in the vans
Donated goods and shop stock left in a van overnight are not usually covered by the motor policy.
- Often part of the charity's property cover
- Overnight conditions are common
- High-value donations may need declaring
Trailers and fundraising kit
Vans towing trailers of stalls and equipment to events need towing declared.
- Trailer value and contents asked for
- Use at events away from base
- Borrowed trailers worth mentioning
How it works
One quote form, specialist fleet brokers
Insure Fleet is an information site, not an insurer or a broker. We link you to MyMoneyComparison.com, a comparison service that gives businesses a gateway to brokers who arrange fleet insurance every day.
Start your quote
Get my fleet quote takes you to our partner, MyMoneyComparison.com.
Describe the charity's vehicles
The form asks about the vehicles, the work they do and who drives, so you can be matched with a specialist fleet broker.
Compare and decide
A broker contacts you with options, subject to insurers' acceptance criteria. There is no obligation to buy.
Before you buy
Questions for the broker about a charity fleet
Charities usually discover the limits of a policy when a volunteer is involved in a claim. These are the points worth raising before then.
- Is there an upper age limit for volunteers?Retired drivers are common, and limits vary between insurers.
- Do volunteers need to be named?Some policies allow open driving with conditions instead.
- Are donated goods in the vans covered?Stock left overnight may need a separate policy.
- Can vehicles be lent to partner groups?Lending is often excluded unless agreed in advance.
- Will a hire van stand in after an accident?Collections and shop runs stop while a van is off the road.
- Are passengers in wheelchairs covered?Lifts, ramps and restraints usually need declaring.
FAQs
Charity fleet insurance questions
What is charity fleet insurance?
Charity fleet insurance is a fleet motor policy for vehicles owned or leased by a charity, community group or voluntary organisation. Vans, minibuses and cars sit on one schedule with one renewal date, and the driver terms are set to suit staff and volunteers.
Is volunteer driver insurance part of a charity fleet policy?
When volunteers drive the charity's own vehicles, they are covered by the charity's fleet policy if they meet its driver terms. When volunteers drive their own cars, they rely on their own motor insurance, which may need volunteering to be declared.
Does charity minibus insurance need a permit?
If passengers are not charged anything, a permit is not usually involved. Charging fares, or asking for donations in return for travel, usually means the minibus needs a permit, and the insurance needs to reflect that work. The details are a question for the broker.
Can a charity with only two or three vehicles get fleet cover?
Many can, though the minimum fleet size depends on the insurer. Smaller charities moving from separate policies may find small fleet insurance a useful starting point.
Does the fleet policy cover school transport contracts?
Not usually. A charity taking on council contracts to carry pupils is doing a different kind of work, which is covered on school transport fleet insurance.
Are donated vehicles harder to insure?
Not usually harder, but older donated vans may have higher mileage or missing records. Insurers will want the vehicle's age, value and condition, and a recent service history helps.
Does Insure Fleet sell insurance?
No. Insure Fleet is an information site and an affiliate of MyMoneyComparison.com, a comparison service that gives businesses a gateway to specialist brokers. When you start a quote you continue to MyMoneyComparison.com, and we may be paid a small commission if you are matched with and speak to a broker.
Ready to insure your charity's vehicles together?
One form for vans, minibuses and cars, specialist brokers, no obligation.